
Validate demand fast: interview 20 target buyers, run two landing-page tests, and aim for 10% qualified conversion plus five pre-orders before you build a two-week paid MVP. Benchmark competitors to find a clear wedge, then pick sole trader for simplicity or a limited company for liability protection and B2B trust. Register promptly with Companies House/HMRC, open a business bank account, and use tight contracts and insurance. Price with VAT and margins, ring-fence tax weekly —next you’ll see the exact checklists and numbers.
Key Takeaways
- Validate demand early: interview 20 target buyers, run two landing-page tests, and aim for 10% qualified conversion plus five pre-orders.
- Build a two-week MVP, charge from day one, and track retention, usage, and churn weekly to pivot fast.
- Choose the right structure: sole trader for simple low-risk work; limited company for liability protection, B2B trust, and higher profit plans.
- Set up compliance immediately: incorporate correctly, open HMRC accounts, and track deadlines for Corporation Tax, VAT, PAYE, and confirmation statements.
- Price and manage cash tightly: use fully loaded costs, protect margins, ring-fence VAT/tax weekly, and stress-test runway for slower sales and late payments.
Validate Your UK Startup: Demand, Competitors, MVP
Before you spend serious money, prove your UK startup solves a real problem for a real, reachable market.
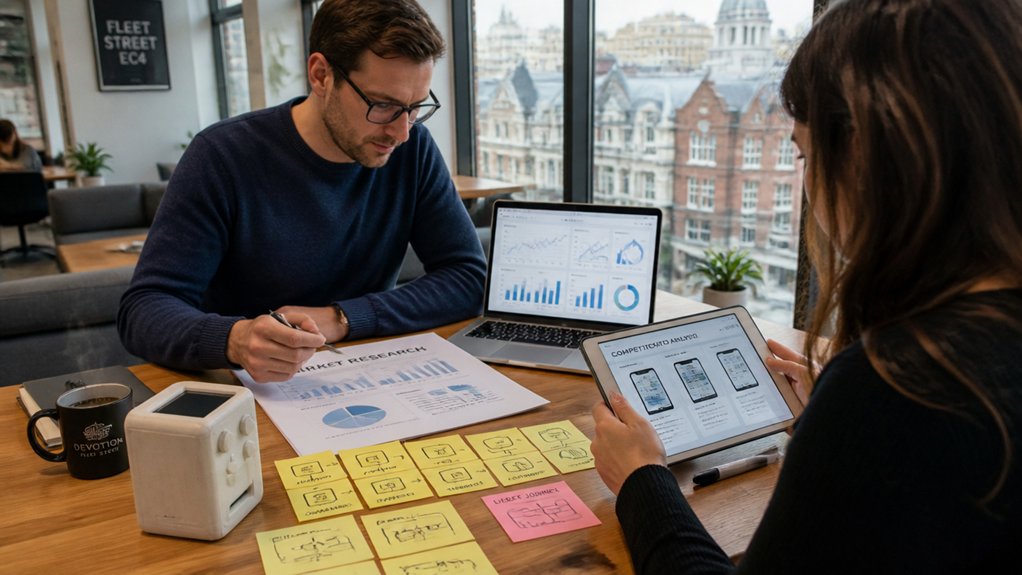
Start with Market research: interview 20 target buyers, run 2 landing-page tests, and track sign-ups, click-through rate, and willingness-to-pay. Aim for at least 10% conversion from qualified traffic and five people ready to pre-order.
Next, do competitor analysis: list direct and indirect rivals, compare pricing, channels, and review themes on Google, Trustpilot, and app stores. Identify one clear wedge—faster setup, lower total cost, or a niche segment competitors ignore.
Build an MVP that tests that wedge only. Ship in two weeks, charge from day one, and measure retention, repeat usage, and churn weekly. If metrics stall, pivot fast.
Pick a UK Structure: Sole Trader vs Limited Company
Once your demand tests and MVP numbers show you’ve got traction, lock in a legal structure that won’t trip you up on tax, liability, or admin.
If you’re testing low-risk services, a sole trader setup keeps costs and paperwork lean, but you stay personally liable for debts and claims—key Legal considerations when you’re signing contracts or handling customer data.
A limited company ring-fences liability, looks stronger to B2B buyers, and can help when you’re hiring or raising capital.
Compare tax implications using real projections: estimate next 12 months’ profit, salary/dividend mix, and reinvestment needs.
If profits will stay modest and simplicity matters, sole trader often wins.
If you expect higher profit, external funding, or legal risk, choose limited early.
Register With Companies House and HMRC (Fast Checklist)
Lock in your structure (sole trader or limited company) because it determines your deadlines, reporting, and tax exposure.
If you’re forming a limited company, file your incorporation with Companies House and get your company number so you can legally trade and open accounts.
Then set up your HMRC accounts—Corporation Tax (if applicable), PAYE if you’ll pay staff (including yourself as a director), and VAT if you’ll hit the threshold or need it for credibility.
Choose Company Structure
A smart company structure choice can cut your tax bill, limit personal liability, and speed up compliance from day one, so don’t default to “limited company” without checking the facts. Start with your risk profile: if you’ll sign leases, hire staff, or handle client data, limited liability often beats sole trader exposure.
Next, model tax: estimate profit, then compare Income Tax + NICs versus Corporation Tax plus dividend planning. If you’re reinvesting profits, a company can be more efficient; if you’re extracting most income, sole trader may win.
Check Legal compliance workload: accounts, payroll, VAT, and record-keeping. Protect Intellectual property early—assign IP to the right entity and document ownership.
Finally, choose partners carefully: a partnership can amplify liability unless structured properly.
File Companies House Registration
If you’re setting up a limited company, get Companies House and HMRC registration right upfront—errors in names, SIC codes, or share structure can trigger rejections, delays, and avoidable admin later. Use Companies House Web Incorporation to file faster and pay the standard fee.
Before you submit, run this checklist: confirm a unique company name and registered office; choose correct SIC codes; set directors, PSC details, and service addresses; define share classes, number of shares, and allotment; upload accurate articles (use Model Articles unless you’ve got custom terms).
Double-check dates of birth and nationalities to avoid mismatches. Keep copies of the IN01 and confirmation statement due date. This locks in Company compliance and helps you meet legal obligations from day one.
Set Up HMRC Accounts
Once Companies House confirms incorporation, set up your HMRC accounts straight away so you don’t miss statutory deadlines or cash-flow planning. Activate your Government Gateway and enroll for Corporation Tax: you must tell HMRC your company’s “active” within 3 months of starting to trade.
Put the Corporation Tax payment date in your calendar (usually 9 months and 1 day after your accounting period ends).
Next, decide if you’ll run payroll. If you’ll pay yourself or staff, register as an employer before the first payday and set up RTI submissions.
Check VAT: if taxable turnover will exceed £90,000 in any 12-month period, register promptly; don’t backdate accidentally.
Store logins, UTR, and filing dates to maintain HMRC compliance and stay ahead of tax obligations.
Set Up Business Banking, Insurance, and Contracts
Next, you’ll lock down the basics that protect cashflow and reduce risk: pick a bank that fits your transaction volume, fees, and integrations, then open a dedicated business account.
You’ll also arrange essential insurance (at minimum employers’ liability if you hire, plus public/professional liability as needed) so one claim doesn’t wipe out your runway.
Finally, you’ll draft clear contract templates—scope, pricing, payment terms, IP, liability caps, and termination—so every deal runs on the same rules.
Choose The Right Bank
Where you bank can quietly add hundreds of pounds a year to your overhead, so choose your business account like a supplier, not an afterthought.
Start by listing your transaction profile: monthly inbound payments, card spend, cash deposits, and international transfers.
Then compare Bank fees line by line: monthly fee, per-transfer charges, FX markup, cash handling, and card replacement.
Prioritise digital banking if you invoice, reconcile, or travel: look for fast onboarding, UK account details, app approvals, instant notifications, and Open Banking feeds into Xero/QuickBooks.
Check limits and service levels: Faster Payments cut-off times, chargeback support, and phone access when something breaks.
Run a 90-day trial, track total costs, and switch if fees or friction exceed your baseline.
Arrange Essential Business Insurance
Although it can feel like a grudge purchase, business insurance is one of the cheapest ways to stop a single incident from wiping out your cash flow.
Start with your biggest exposures: public liability if customers or suppliers visit you, employers’ liability if you hire staff (it’s legally required), and professional indemnity if you give advice or deliver services.
Then price-test Insurance coverage against real numbers: worst-case claim size, replacement costs for kit, and your monthly revenue.
Raise your excess to cut premiums, but only if you can pay it tomorrow.
Bundle policies only when the combined limit and exclusions still match your risks.
Treat it as risk management: document controls (training, fire/security, backups) because insurers often discount well-run operations.
Review annually after growth, new hires, or new locations.
Draft Clear Contract Templates
How do you stop scope creep and late payments from draining your time and cash? You lock in expectations with repeatable contract templates. Start with tight Legal agreements: scope, deliverables, milestones, and acceptance criteria.
Add change-control language so extras require written approval and a revised fee. Set payment terms upfront: deposit, staged invoices, late fees, and suspension rights if payment slips.
Use plain-English liability caps, IP ownership, confidentiality, and termination clauses to reduce disputes. For Contract drafting, standardise a proposal-to-contract workflow: quote number, start date, and signatures via e-sign tools.
Track key data—average days to pay, change requests, and write-offs—then adjust terms quarterly. If you’re unsure, get a UK solicitor to review once and reuse.
Price for Profit (Include VAT and Margins)
Before you set a price, lock in the profit you need by building VAT and your margin into the numbers from the start. Start with your fully loaded unit cost (materials, labour, tools, delivery, and a realistic overhead rate).
Decide the profit margins you’re targeting (e.g., 30–50% for services, 10–25% for products), then compute: Net price = Cost ÷ (1 − margin).
If you quote VAT-inclusive, calculate: Gross price = Net price × 1.20 and show both figures on quotes and invoices to prevent “VAT shock”.
Stress-test your pricing strategies by tracking win rate, average discount, and gross margin per job weekly. If discounts push margin below your floor, change scope, not price.
Keep a one-page pricing sheet.
Handle VAT, PAYE, and Corporation Tax Basics
When should you start treating VAT, PAYE, and Corporation Tax like core operating costs, not “accounting later”? From day one—because cash timing, not profit, kills small firms. Track VAT on every invoice and expense, and set aside the VAT you collect weekly so you’re never scrambling at quarter-end. Register when you must, but also when clients expect it; missed VAT compliance triggers penalties and blocks refunds.
If you hire, run payroll properly before the first payday. Tight PAYE administration means accurate RTI submissions, correct tax codes, and employer NIC budgeting.
For Corporation Tax, forecast your taxable profit monthly, ring-fence a percentage in a separate account, and log allowable expenses with receipts. File on time, reconcile regularly, and you’ll avoid surprises.
Fund Your UK Business: Bootstrapping, Loans, Equity
Most UK startups fund their first 6–18 months with a mix of bootstrapping, debt, and equity, and the right choice comes down to cash-flow predictability and the cost of capital.
Start by bootstrapping if you can reach breakeven fast: cut burn, invoice early, and track runway weekly.
If revenue is steady, compare loans (bank, Start Up Loans, CBILS-style alternatives) by APR, fees, covenants, and repayment flexibility; keep debt service under 20–30% of monthly gross profit.
If growth is capital-hungry, raise equity, but anchor your Business valuation with traction metrics: MRR, churn, CAC payback, and gross margin.
Stress-test Funding options with a downside case: 30% lower sales and 60-day payment terms.
Document assumptions and update monthly.
Hire in the UK: Contractors, IR35, and Payroll
Once you’ve picked a funding mix and mapped your runway, your next cost lever is hiring—because payroll and contractor spend often become the biggest monthly outflow after software and rent.
Model costs per role: gross salary + employer NI + pension (3% minimum) + benefits, then add 10–15% contingency for churn and sick cover.
If you use freelancers, tighten contractor management: define deliverables, limit control over hours, avoid exclusivity, and keep substitution rights real.
Run an IR35 compliance process for every engagement, document status determinations, and price for “inside IR35” (PAYE via umbrella) versus “outside” rates.
Set up payroll early: choose software, register for PAYE, automate pensions, and reconcile RTI monthly.
Review headcount monthly against runway and revenue.
Conclusion
You’ve now got a clear UK startup playbook: validate demand, choose the right structure, register fast, and lock down banking, insurance, pricing, and tax basics. Keep it lean, then fund and hire with eyes open to IR35 and payroll. Here’s the kicker: around 60% of UK small businesses fail within five years. So measure traction weekly, watch cash daily, and fix margins before you chase growth. Execute, review, repeat.